
Three-minute read
Iran’s clerical dictatorship is responding to its worsening financial crisis not with evidence of restored confidence, but with an expanding web of emergency interventions: selling dollars, restricting cryptocurrency markets, pursuing exporters for missing foreign currency, tightening pressure on troubled banks and trying to prevent savings from fleeing into gold and dollar-linked assets.
The regime presents these measures as signs of control. Its own media tell a less reassuring story.
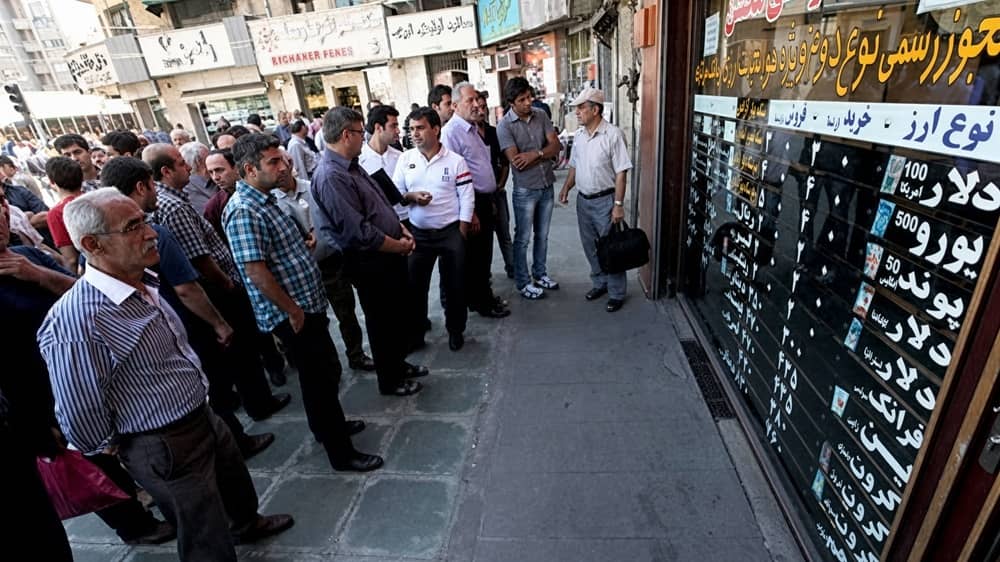
In early October, the Central Bank launched a $2 billion intervention after the dollar surged toward 270,000 tomans. Tasnim later acknowledged that selling currency had produced only a temporary retreat and argued that increasing supply alone could not solve the problem.
Dollars for Everyone—Except Those Who Cannot Afford Them
The Central Bank then tried another extraordinary measure: allowing every Iranian over 18 to buy up to $10,000 through selected banks using a national ID.
The policy was presented as a way to draw demand away from the open market. But it immediately exposed another contradiction inside the regime. Tehran MP Mehdi Koochakzadeh pointed out in parliament that buying the full allocation required roughly 2.5 billion tomans—an amount far beyond the reach of ordinary Iranians already struggling with basic living costs. Even Parliament Speaker Mohammad-Bagher Ghalibaf said he was surprised when he learned of the scheme and questioned why it was being implemented.
What officials advertise as broad public access to foreign currency therefore functions merely as another channel through which those with capital can protect themselves from the currency crisis.
Why the Iranian Regime Chose War and #Economic Siege Over an Ideal Deal
by @HakamianMahmoud https://t.co/Dxg60oscz5— NCRI-FAC (@iran_policy) August 26, 2026
Chasing Dollars That Never Came Back
Another admission came from Central Bank Governor Abdolnaser Hemmati himself.
According to state broadcaster reporting, Hemmati has said roughly $21 billion in export earnings had failed to return to the country’s economic cycle since the beginning of the previous Iranian year, although authorities had identified around $13 billion that they expected eventually to recover. He thanked the judiciary and other agencies for helping pursue the funds. The same report said around $195 million was being traded daily through the official exchange center.
That is a remarkable backdrop to official claims of abundant foreign currency. The Central Bank is simultaneously telling the public that it has plenty of dollars while mobilizing the judiciary to retrieve billions that exporters have not brought home.
Hemmati has nevertheless continued declaring that the country has ample foreign exchange—telling state television recently, in effect, “we have currency, and plenty of it.” The contradiction is increasingly visible in the regime’s own reporting: if supply were genuinely comfortable, the state would have far less reason to chase exporters, ration access and deploy increasingly intrusive controls.
"Washington was prepared to provide a financial and #diplomatic lifeline; however, Tehran's regime lacked both the will and the capacity to play along. Because it is too weak and fragile to accept it," @MehdiOghbai writes.https://t.co/6R3QiV6hSS
— NCRI-FAC (@iran_policy) July 14, 2026
Tether Becomes the Next Target
The regime has also moved against one of the principal alternatives Iranians use to escape depreciation: Tether, the dollar-linked cryptocurrency.
Fars reported that the Central Bank was preparing to block bank accounts and toman payment gateways belonging to some cryptocurrency exchanges, accusing platforms of artificial orders and speculation that allegedly affected the Tether price and, in turn, the currency market. The same reporting said nighttime Tether trading had already been curtailed.
Earlier restrictions had already halted Tether trading overnight and capped purchases at 2,000 Tether per user per day. The significance is obvious. Instead of persuading Iranians that holding tomans is safe, the authorities are trying to make it more difficult to move out of them.
The same logic has extended to gold and foreign currency. The Central Bank has prohibited banks from extending credit for purchases of gold, foreign currency and cryptocurrencies—another attempt to prevent bank liquidity from feeding demand for assets citizens regard as protection against inflation.
"On the morning after the ceasefire, every exhausted and exasperated mind, long numbed by the #IranWar, will turn instinctively toward the search for real change and the practical means to bring this regime to an end." https://t.co/8Tmh0Sl0Kc
— NCRI-FAC (@iran_policy) April 9, 2026
Liquidity Is Becoming Harder to Contain
The underlying monetary problem is just as serious.
Hemmati acknowledged in state-media interviews that liquidity growth had accelerated sharply under wartime and fiscal pressure and that the authorities were trying to curb government reliance on Central Bank financing. He has also threatened action against banks whose balance sheets remain severely imbalanced.
IRNA carried his argument that inflationary pressure would ease as liquidity growth slowed, while simultaneously reporting the Central Bank’s continued dollar sales and efforts to keep foreign exchange flowing to food, medicine and industrial inputs.
These are not signs of a financial system returning to normal. They are signs of authorities trying to prevent several pressures from feeding one another: currency depreciation, inflation, bank instability, capital flight and demand for alternative stores of value.
"The regime finds itself trapped between the prospect of renewed foreign #IranWar and the danger of a people’s armed uprising. As a result, Tehran is increasingly resorting to wartime posturing," @MansoreGolestan writes.https://t.co/y4QCukZXPw
— NCRI-FAC (@iran_policy) May 20, 2026
A Crisis of Money—and of Trust
Iran has endured economic siege before. Under Dr. Mohammad Mossadegh, when Britain moved to choke off oil revenues, the government appealed directly to the public. Iranians bought national bonds, donated savings and, in documented cases, sold personal jewelry to help a government they believed was defending the country’s sovereignty.
Today, the relationship between state and society is profoundly different. After nearly half a century of clerical rule, the regime confronts not only mounting pressure from abroad but deep anger at home over economic hardship, repression and the costs of its policies.
That is the larger danger behind the financial crisis. Tehran is being squeezed simultaneously by an international community increasingly determined to impose costs on its conduct and by a population forced to bear those costs at home. The reckoning the regime has long tried to postpone is increasingly coming from both directions at once.